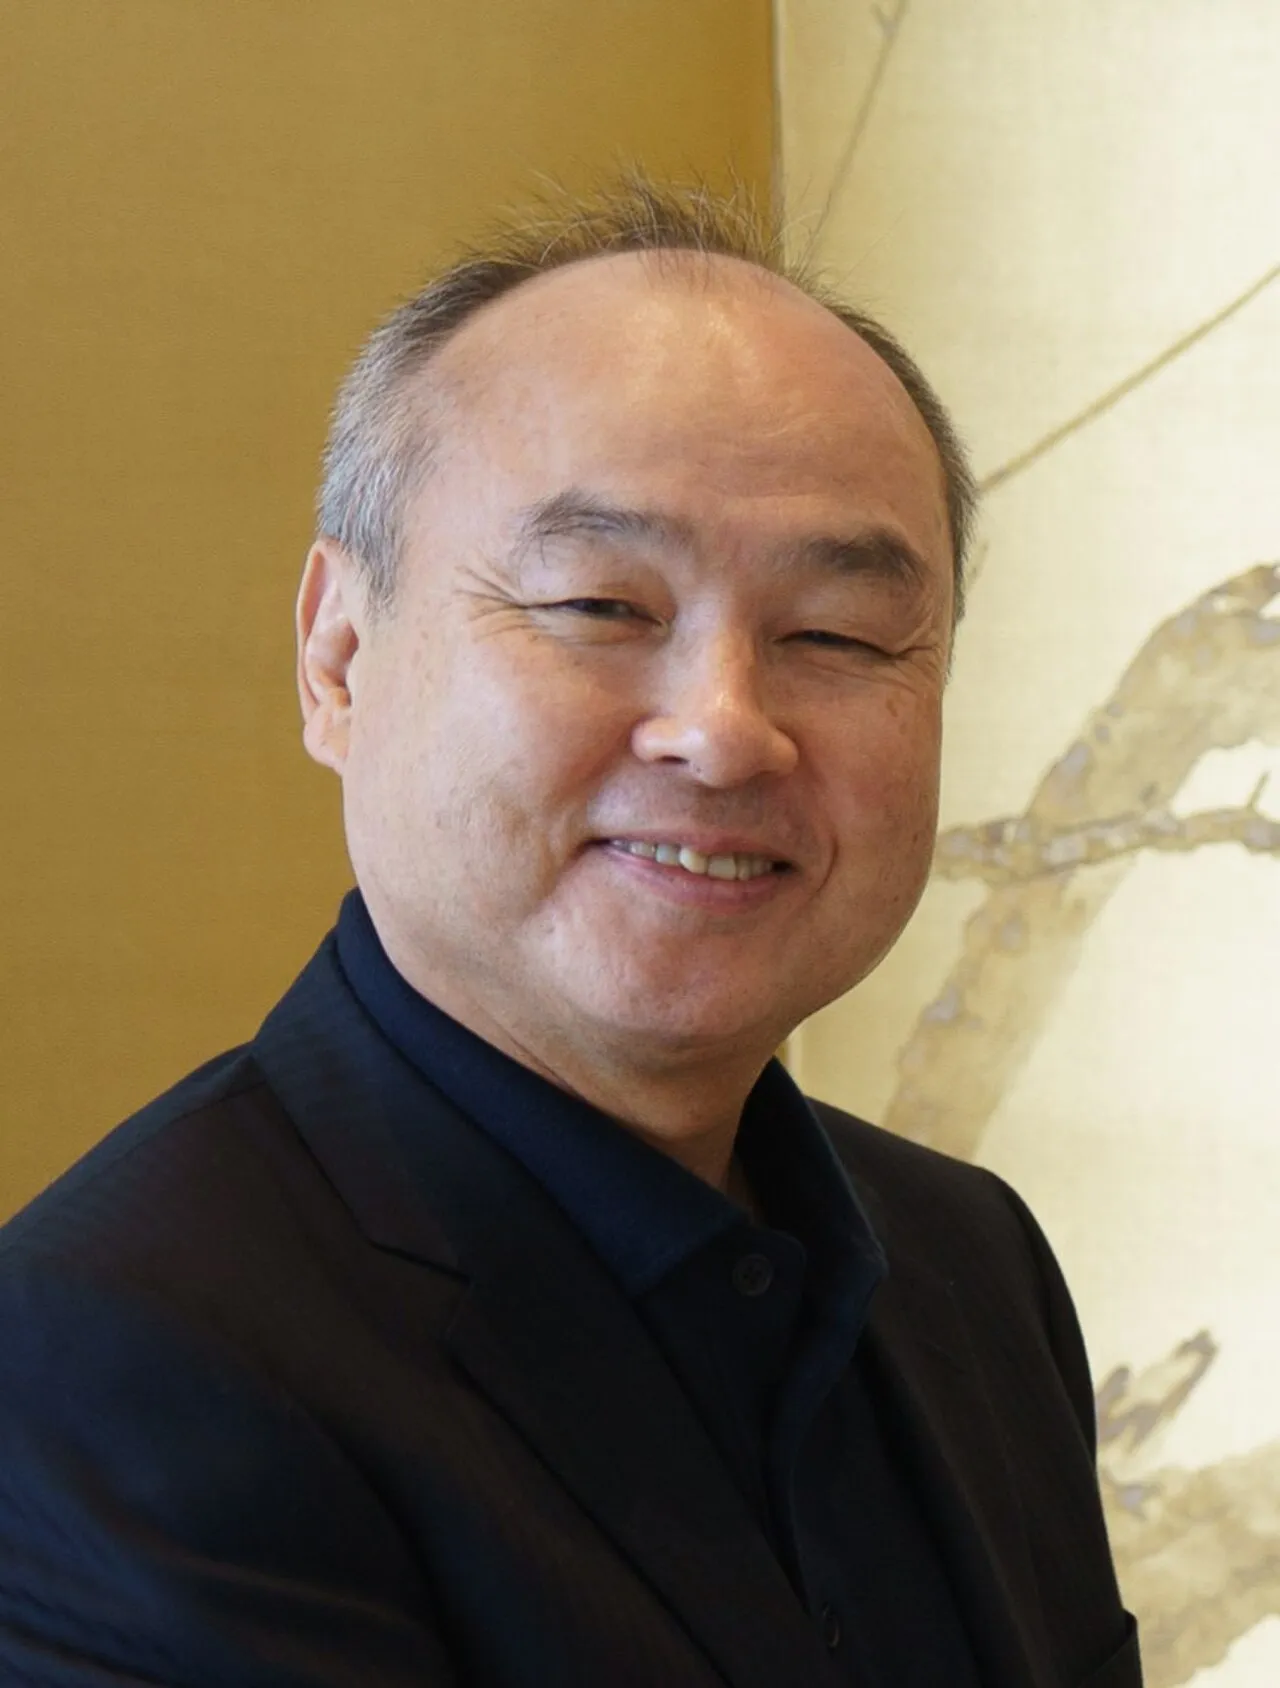
The Man Who Bet on Eyes
A Korean kid in Japan endured bullying and left at sixteen. He sold a dictionary to Sharp and built a software bank. Then he turned SoftBank into a bet on the entire Information Revolution.
On June 2, 2026, SoftBank Group's market value passed Toyota's and briefly made Japan look different on a stock screen. Forbes's realtime list put Masayoshi Son near one hundred billion dollars. For a few days he was Asia's richest person again after more than a decade. Three days later SoftBank shares cooled, about thirteen billion dollars of paper wealth vanished from the same list, and Mukesh Ambani and Gautam Adani moved back ahead. Son did not treat the yo-yo as the point. In his SoftBank Group Report letter dated June 24, 2026, he pointed at something quieter and larger: SoftBank's net asset value, the value of its holdings minus net debt, had reached about seventy-four trillion yen as of June 23, roughly twice the group's then market capitalization of thirty-seven trillion yen. The market, he argued, still priced the goose as if it were only the eggs you could already count.
That sentence is the drama of his life. Son is not a founder who shipped one product and retired into myth. He is a founder who keeps rewriting the product. Software wholesaler. Magazine publisher. Broadband fighter. Mobile carrier. Sprint shareholder. Arm owner. Vision Fund rainmaker. WeWork casualty. OpenAI and Stargate backer. At sixty-eight he publicly updated the fifty-year life plan he wrote at nineteen so he could keep chasing Artificial Superintelligence into his seventies. The through-line is not calm. It is appetite with a schedule.
Tosu, bullying, and a plane ticket to Tokyo
Masayoshi Son was born Masayoshi Yasumoto on August 11, 1957, in Tosu, Saga Prefecture, on Japan's southern island of Kyushu. His family was Zainichi Korean. His grandfather had come from Daegu and worked as a miner. His father raised pigs and chickens, ran into trouble with authorities over land, then built an illegal sake business that did well enough for the family to own the first car in town. They moved so the children could attend a better school. At home the Korean name stayed quiet. At school the difference did not.
Son has said he was bullied for his background and at one point thought about ending his life. Discrimination did not make him soft. In interviews he has framed it as fuel that made him work harder. That framing is his. The facts underneath are harder: a minority kid in postwar Japan learning early that belonging could be conditional.
He found a different kind of belonging in a book. Den Fujita, the founder of McDonald's Japan, had written a bestseller that made Son want a meeting. He tried normal channels and failed. So he bought a plane ticket to Tokyo, walked into McDonald's Japan headquarters without an invitation, and got roughly fifteen minutes with Fujita. Fujita's advice was blunt: learn English, learn computers, go to the United States. Son dropped out of high school in Japan. At sixteen he moved to Oakland, California.
Berkeley, five minutes a day, and the first inventions
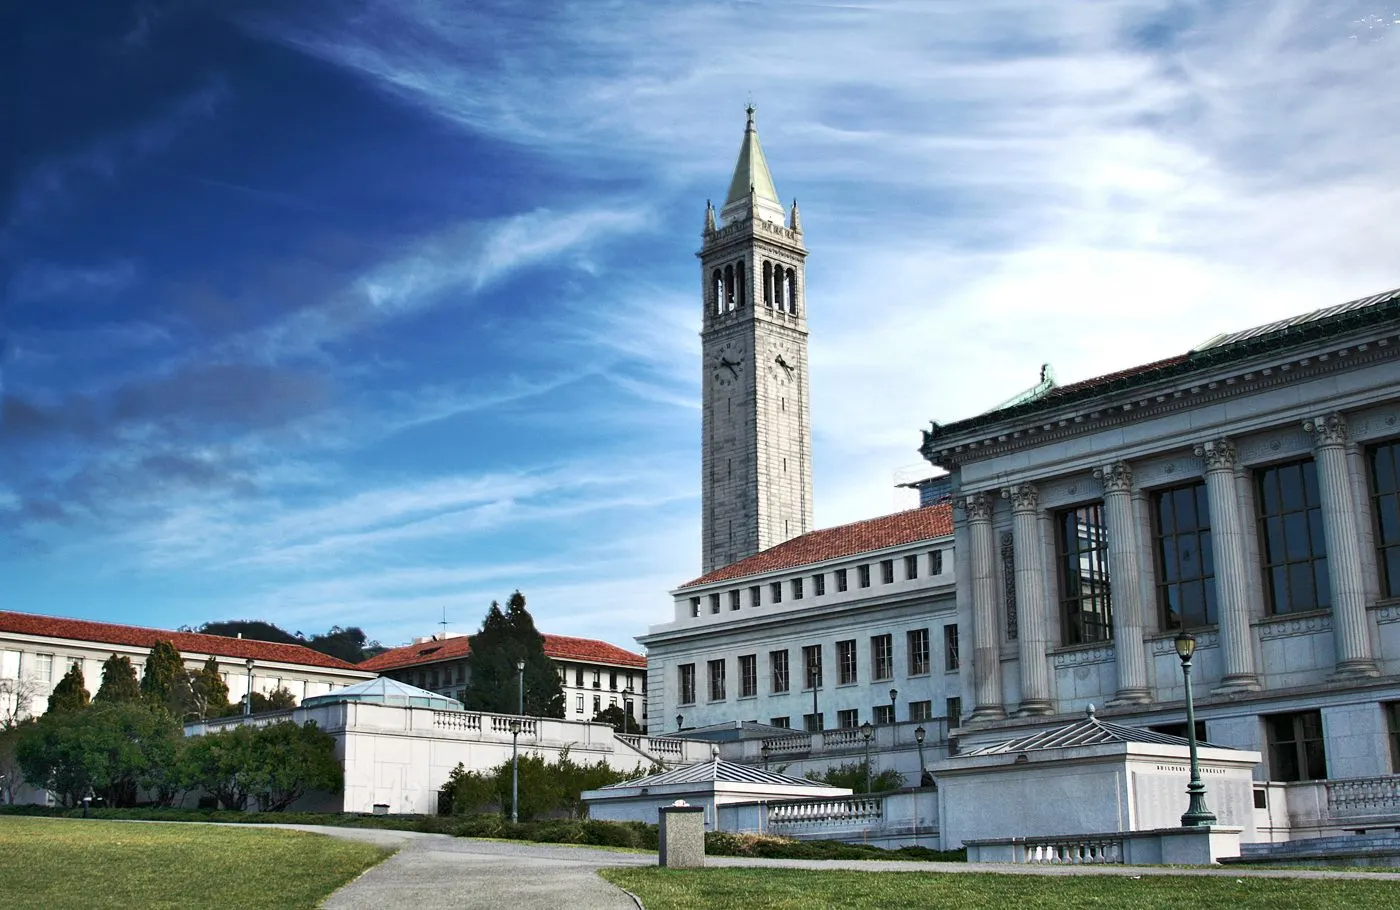
English study at Holy Names College came first. Then Serramonte High School, where he finished requirements in about three weeks. Then the University of California, Berkeley, economics, class of 1980. America did not make him cautious. It made him catalytic.
He rationed himself. In the Rubenstein interview he described a student rule: study hard, but allow five minutes a day for making money, aiming for ten thousand dollars a month. Friends told him it was impossible. He decided the efficient path was invention and patents. He set an alarm, forced ideas in the window, and built an electronic translator. With help from professors including Forrest Mozer, he sold the technology to Sharp for about one point seven million dollars. He imported used video game machines from Japan on credit and installed them in dorms and restaurants for roughly another one point five million. He started Unison World in Oakland and later sold it for about two million dollars; Kyocera would absorb that lineage.
At nineteen he also wrote a fifty-year life plan on paper: establish himself in his twenties, build a war chest in his thirties, take on major challenges in his forties, achieve the vision in his fifties, hand over the business in his sixties. Most nineteen-year-olds doodle. Son treated the doodle like a contract. In 2026 he would reopen that contract and extend it.
He met Masami Ohno at Berkeley. They married in 1979 and later had two daughters. When he returned to Japan he chose to use his Korean surname Son for professional life, against relatives who feared exposure. For many ethnic Korean children in Japan, that public choice mattered as much as any spreadsheet.
SoftBank: a warehouse that thought like a bank
In September 1981 he founded Nihon SoftBank, later SoftBank Group. Personal computers were arriving. Hardware was ahead of software distribution. Son's idea was simple and sticky: aggregate software from small houses, warehouse it, wholesale it to PC stores. A bank of software, not money. Publishing computer magazines and books rode beside the wholesale business. The company grew with Japan's PC boom.
The internet years turned SoftBank from distributor into investor. SoftBank took an early stake in Yahoo while it was still private. In Rubenstein's telling, Son pushed a hundred million dollar investment when Yahoo had only dozens of employees. Yahoo Japan and Yahoo BB later became broadband weapons. SoftBank accumulated heavy debt chasing the wired future, then bought Japan Telecom assets to deepen the footprint. Broadband was not glamorous. It was oxygen for what came next.
Then came the crash. SoftBank's paper wealth collapsed with the dot-com bust. Fortune and later lists often cited Son as the person who had lost the most money in history for a time, more than fifty-nine billion dollars on paper in 2000 alone. Rubenstein asked how it felt to lose about seventy billion in net worth. Son said he was close to falling off a cliff, almost bankrupt, and somehow survived. Survival meant focus: Yahoo BB, phones, cash discipline when the market hated him.
Jack Ma's eyes and a twenty million dollar check
In 2000 SoftBank invested about twenty million dollars in Jack Ma's Alibaba. Son later told Rubenstein the company had no business plan, zero revenue, and maybe thirty-five or forty employees. What he bought was the eyes. "Strong shining eyes," he said. He believed Ma could make young Chinese people follow him. At Alibaba's 2014 IPO that early check was often valued in the tens of billions for SoftBank's stake. Press stories called it one of the great venture returns of all time. SoftBank's Alibaba holding peaked as a central pillar of SoftBank's net assets. Son joined the Alibaba board in 2005 and stepped down in June 2020. By 2023 SoftBank had sold down most of the stake as strategy and China risk shifted. The legend stayed. The balance sheet moved on.
Son has also said he felt stupid for passing early chances at Amazon and Tesla. The confession matters because it shows his method: he is not a perfect oracle. He is a high-conviction pattern matcher who still misses.
Vodafone Japan, the iPhone, and mobile internet
By the mid-2000s Son decided the next stage was mobile internet. He applied for spectrum. The government said no more licenses. So SoftBank bought Vodafone's Japan mobile business in a deal announced in March 2006, on the order of one point seven five trillion yen. Overnight SoftBank became a carrier, not only a software and internet company.
Son's relationship with Steve Jobs became industry lore. SoftBank secured iPhone distribution in Japan. SoftBank and Apple announced the iPhone 3G for Japan on July 11, 2008. The phone remade SoftBank Mobile's brand. Later SoftBank pushed into the United States through Sprint, building a stake that rose into the mid-seventy to mid-eighty percent range before the T-Mobile US merger in 2020 and later stake rearrangements with Deutsche Telekom. The American carrier chapter was messy, regulatory, and expensive. It also taught SoftBank how hard telecom scale fights get outside Japan.
After the Fukushima Daiichi disaster in 2011, Son publicly criticized the nuclear industry and pushed solar and renewable projects. Some Saudi and India megaproject announcements made global headlines; delivery and scale for those visionary grids remained contested in later coverage. The cleaner fact is the posture: when Japan's energy story cracked, he tried to write SoftBank into the rewrite.
Arm after Brexit: buying the chip blueprint
In July 2016, days after the United Kingdom voted for Brexit, SoftBank agreed to buy Arm Holdings for about twenty-four billion pounds, roughly thirty-one to thirty-four billion dollars, the largest purchase of a European technology company at the time. The deal closed that September. Arm did not make the flashiest consumer gadgets. It designed the intellectual property inside countless phone chips and, increasingly, other computers. Son saw a platform under platforms.
In 2020 SoftBank agreed to sell Arm to Nvidia in a cash-and-stock deal announced around forty billion dollars, a price that looked even larger as Nvidia's stock rose. U.S. and European antitrust pressure killed the deal in February 2022. SoftBank pivoted to an Arm IPO. On September 14, 2023, Arm priced American depositary shares at fifty-one dollars and listed on Nasdaq. SoftBank kept a dominant stake, later cited in market coverage near ninety percent. By 2026 Son's letters treated Arm not as a trophy but as the CPU cornerstone for an agentic AI era after the GPU-first chapter. In March 2026 Arm announced an AGI CPU framing aimed at cloud systems for that next phase.
Vision Fund: forty-five billion in forty-five minutes
The SoftBank Vision Fund, launched in 2017, was Son's attempt to industrialize the Alibaba instinct at planetary scale. Nearly one hundred billion dollars. Saudi Arabia's Public Investment Fund became a cornerstone limited partner. Son told Rubenstein the famous meeting with the then deputy crown prince was not one hour for forty-five billion. It was forty-five minutes. His opener was a "Tokyo gift," a "trillion dollar gift": invest a hundred billion, get a trillion back through the singularity thesis that computing would surpass human brains across most domains within decades.
Apple, Qualcomm, Foxconn, Larry Ellison's family office, and others joined. SoftBank poured capital into Uber, DoorDash, Coupang, Grab, Didi, Fanatics, Paytm, Oyo, WeWork, and dozens more. Son talked about personal relationships with portfolio CEOs and a Cluster of No. 1 strategy: assemble category leaders and force synergies. For a while Silicon Valley treated SoftBank checks like weather. Founders priced rounds around Vision Fund gravity. Valuations went vertical.
Then gravity returned.
WeWork, shame, and the broken experiment
WeWork became the emblem. SoftBank and the Vision Fund piled in at giant valuations. The 2019 IPO attempt collapsed under governance and profitability questions. SoftBank took deeper control, wrote down billions, and watched WeWork file Chapter 11 in November 2023. Press tallies of SoftBank's cumulative WeWork losses often sat in the ten-to-fourteen-billion-dollar range depending on method and timing. Other Vision Fund names also cracked: OneWeb, Wirecard exposure narratives, Katerra, Greensill, Oyo stress, Klarna mark-downs. Chinese regulatory pressure hit Didi and the wider China tech book. COVID exposed business models that had been funded as destiny.
For the fiscal year ended March 31, 2022, SoftBank's Vision Fund segment posted a record loss on the order of three point five trillion yen, about twenty-seven billion dollars, as public marks cratered. In August 2022, asked about his track record, Son said he was embarrassed and ashamed. Barron's called the SoftBank experiment failed. The Wall Street Journal labeled SoftBank a big loser of the tech downturn. Bloomberg wrote about a broken business model. These were not anonymous blogs. They were mainstream finance desks describing results SoftBank's own filings made hard to hide.
Governance got personal. In November 2022 the Financial Times reported Son personally owed SoftBank about four point seven billion dollars amid tech losses, with his Vision Fund 2 related economics underwater. Bloomberg in February 2023 put the figure near five point one billion on side deals structured to boost his compensation. Son insisted there was no conflict of interest. Critics saw a founder too entangled with the vehicle he ran. By March 2023, as Silicon Valley Bank failed, reporting noted large SoftBank share collateral for margin loans and doomsday-scenario talk. SoftBank did not die. Son's reputation for invincibility did take a hit.
Vision Fund 2 never matched Fund 1's outside capital. SoftBank increasingly used its own balance sheet. Deal count rose while average check size fell. The machine kept moving. The myth cooled.
How Son works when the room is watching
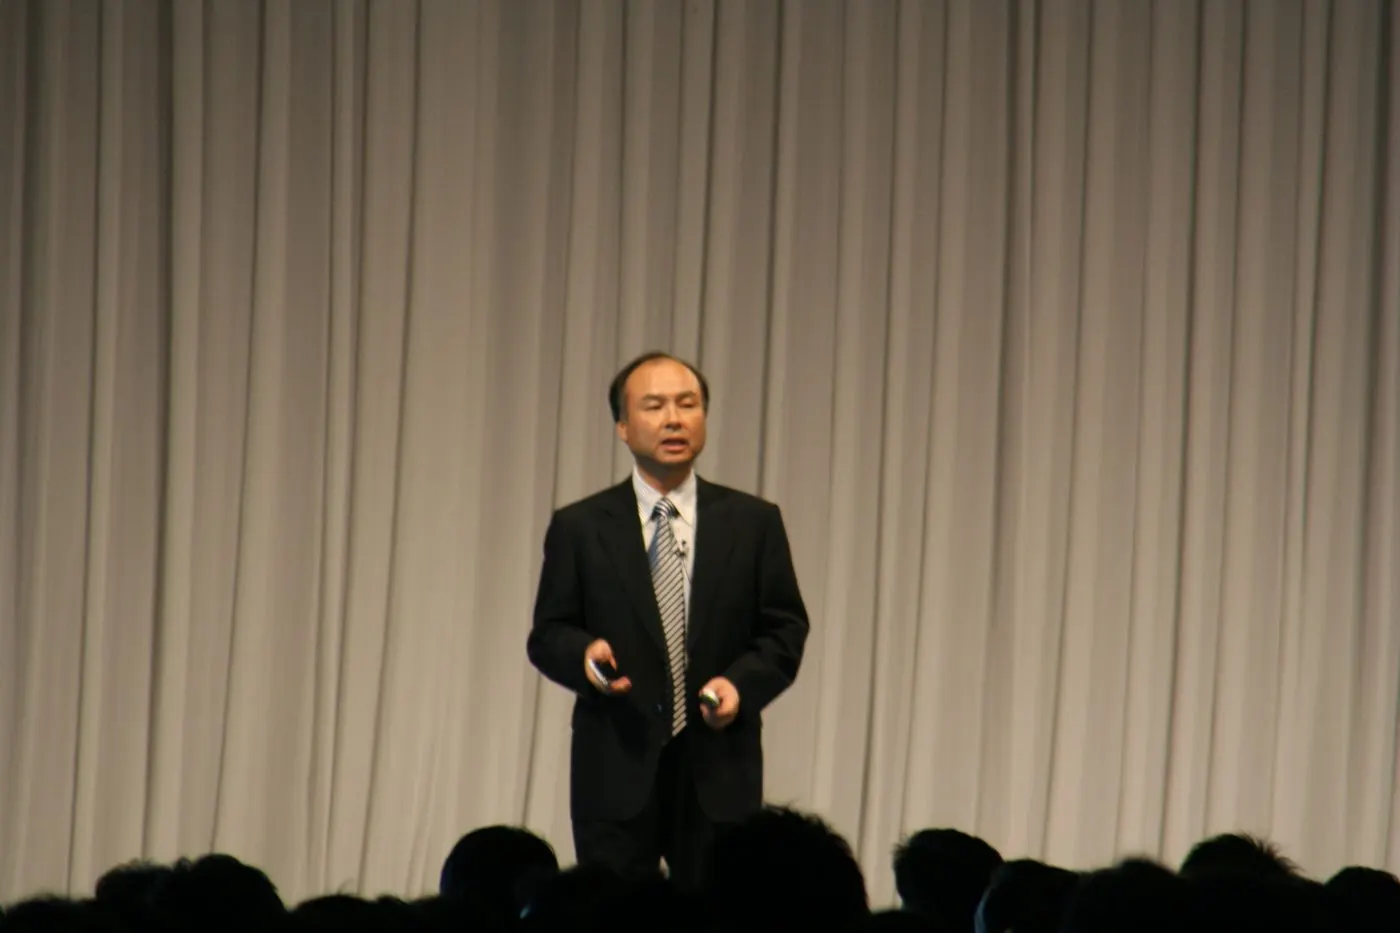
Son's public method is theatrical and specific. He draws fifty-year arcs. He walks into rooms with gifts and singularity slides. He talks about eyes and energy in founders the way other investors talk about unit economics first. He builds "clusters" and hunts for number-one positions. He will spend years on a thesis, then reverse when antitrust or markets force it, as with Nvidia-Arm. He will apologize in earnings season when the numbers demand it, then raise the next audacious target anyway.
Inside SoftBank Group he remains the center. Company biographies still list him as founder, chairman, and CEO across four decades. As of June 1, 2026, SoftBank said he held about one point eight six billion shares. Outside SoftBank he chairs Arm and Stargate. He owns the SoftBank Hawks baseball club. He is known for Burgundy wine and for houses that look like sci-fi sets, including a Tokyo mansion with a golf range that can mimic weather from famous courses, and a Woodside, California home reported near one hundred seventeen million dollars. The lifestyle reads like victory. The Vision Fund years proved victory can still write down.
Legal care matters on the ugly chapters. WeWork's collapse, portfolio mark losses, and personal loan balances are company disclosures and major-newsroom reporting. Son's shame quotes are his own words on the record. Motives inside private meetings are not fully public. A fair story holds the losses without inventing cartoon villainy, and holds the wins without erasing the body count of failed bets.
OpenAI, Stargate, and the AI stack bet
ChatGPT's explosion gave Son a new mountain that looked like his old mountain. SoftBank, through SoftBank Vision Fund 2, began investing in OpenAI in September 2024. By February 27, 2026, SoftBank announced a further thirty billion dollar follow-on into OpenAI Group PBC at a seven hundred thirty billion dollar pre-money valuation, in three ten-billion-dollar tranches on April 1, July 1, and October 1, 2026, Japan time. SoftBank said the cumulative investment would reach about sixty-four point six billion dollars and roughly thirteen percent ownership if completed. The first two tranches funded on schedule. The third remained on the October calendar as of SoftBank's later updates. SoftBank arranged large bridge facilities and sold assets, including a November 2025 sale of its Nvidia stake for nearly six billion dollars reported by Reuters, to help fund the OpenAI push.
On January 21, 2025, SoftBank, OpenAI, Oracle, and MGX announced the Stargate Project: up to five hundred billion dollars of AI infrastructure in the United States over roughly four years, beginning with about one hundred billion dollars of deployment. SoftBank took financial lead responsibility. OpenAI took operational lead. Masayoshi Son became chairman. Reporting described SoftBank and OpenAI each around forty percent, with Oracle and MGX smaller, plus debt and limited partners. Buildout talk centered first on Texas, including Abilene campuses, then widened. Critics including Elon Musk questioned whether the money was truly lined up. Arm CEO Rene Haas publicly called the backing solid. SoftBank's own later letters treated Stargate as one piece of a four-corner ASI board: frontier models (OpenAI), semiconductors (Arm), infrastructure and power (data centers, Ohio and France projects), and robotics (portfolio companies plus a planned acquisition of ABB's robotics business announced October 8, 2025, expected to close late 2026 for about five point four billion dollars).
In May 2026 SoftBank announced plans for five gigawatts of AI data center capacity in France. In March 2026 a U.S. Department of Energy partnership narrative included ten gigawatts of power and ten gigawatts of AI data center capacity in Ohio. Son's June 2026 CEO letter said he used ChatGPT many times a day as a sounding board, then zoomed out to Artificial Superintelligence: not only smarter models, but intelligence aligned with human reason and morality, eventually embodied in robots that can work in dangerous and difficult places. He compared SoftBank's position to Othello: secure the four corners and the board can flip.
2026 scoreboard: NAV, profit, and a renamed life plan
SoftBank's fiscal year ended March 31, 2026, according to Forbes profile figures circulating in 2026, showed about five trillion yen in net profit on about seven point eight trillion yen in sales. SoftBank's own Group Report materials put NAV at a record forty point one trillion yen at that fiscal year-end, then about seventy-four trillion yen by June 23, 2026, after Arm, SoftBank Corp, and OpenAI-linked marks moved. LTV, SoftBank's leverage-to-value comfort metric, was described near seventeen percent with a cash position around three point five trillion yen at fiscal year-end. Management talked about forty-four billion dollars of investments in fiscal 2025 including OpenAI follow-ons and Ampere, funded with bridge loans and nearly fifty billion dollars of asset sales and bond issuance.
Son's personal wealth swung with SoftBank's share price. Forbes realtime prints in early June 2026 showed him near one hundred billion and briefly Asia's richest, then down more than ten billion within days. Other Forbes snapshots in the same broad period showed lower marks. SoftBank stock is the main engine; exact personal net worth is a moving estimate, not a bank statement.
The emotional update landed in the same June 24, 2026 letter. The nineteen-year-old plan said hand over in the sixties. The sixty-eight-year-old chairman said he still had more to give for another ten or fifteen years. The new mission language was blunt: become the number-one ASI platform provider for the world, not only Japan. He recalled his father's dying words and an older lesson: do not live for money; live to make people happy. He tied SoftBank's founding philosophy, "Information Revolution - Happiness for everyone," to a NAV target of one quadrillion yen by 2042. Whether that number is prophecy or theater, it is consistent with how Son has always managed attention: set a horizon so far that critics sound small, then use capital markets to march toward it.
World change you can touch
Son's impact is not one app icon. It is infrastructure people forget to notice.
Japan's software distribution and PC publishing in the 1980s and 1990s helped a generation of machine users get programs into shops. Yahoo Japan and SoftBank broadband wired households that later became smartphone households. SoftBank Mobile's iPhone era changed how Japan felt the modern phone. Arm's designs sit under vast stretches of the mobile and embedded computing world; SoftBank's ownership and IPO kept that IP company in a SoftBank-centered orbit just as AI training and inference made chips geopolitical. The Vision Fund distorted startup finance for half a decade: bigger rounds, faster unicorn minting, and a painful education in what happens when capital outruns governance. WeWork's failure became a global case study in founder excess and investor complicity. OpenAI's scale, partly funded by SoftBank's tens of billions, is reshaping how students write, how engineers code, and how companies budget for intelligence as a utility. Stargate's data centers, if built at the promised gigawatt scale, will reshape local power grids, construction employment, and the physical footprint of AI in Texas, Ohio, France, and beyond.
There is a shadow ledger. Paper losses destroyed pensions and paper fortunes inside SoftBank's own shareholder base during crash years. Startup employees who believed Vision Fund valuations were destiny learned otherwise. Telecom customers lived through merger politics. AI energy demand raises climate and community fights SoftBank now helps intensify even as Son once waved the solar flag. Holding all of that in one biography is the point. Son's career is a amplifier. Amplifiers do not only play beautiful songs.
Second acts inside the same company
What makes Son unusual is that SoftBank kept being SoftBank while the definition changed. Many founders leave and angel-invest. Son stayed CEO and reinvented the holding company under himself: from software bank to internet conglomerate to carrier to investment vehicle to AI platform thesis. He stepped back from SoftBank Corp's mobile day job in 2021 while remaining founder-director, clearing calendar for group strategy. He left Alibaba's board when the China chapter cooled. He tried to sell Arm to Nvidia, failed, and listed it instead. He absorbed Vision Fund humiliation and then wrote larger OpenAI checks than most sovereign funds.
The Cluster of No. 1 idea is his organizational religion. Buy or back the leader in a category. Connect them. Aim for synergies that a passive index cannot create. Critics say the synergies were often slides. Supporters point at Arm plus OpenAI plus power projects as a more coherent stack than WeWork plus Oyo plus office furniture dreams. SoftBank's 2026 letters lean hard into that stack story. Markets still apply a conglomerate discount. Son still insists the goose is worth more than the visible eggs.
Sprint, T-Mobile, and the American bruising
SoftBank's American carrier chapter deserves its own scar tissue. Son did not dabble. SoftBank bought into Sprint and climbed toward roughly three-quarters and then more than eighty percent ownership through the 2010s. The thesis was familiar SoftBank logic: scale plus spectrum plus a willingness to lose money while the network caught up. Sprint's brand was tired. Integration was hard. U.S. telecom politics were harder. The proposed Sprint and T-Mobile US merger spent years in regulatory weather before closing in 2020 as an all-shares deal around twenty-six billion dollars. SoftBank later reshaped its exposure through Deutsche Telekom, including reported stakes and share swaps that left SoftBank less of a direct U.S. wireless operator and more of a financial claimant on the combined story.
The lesson for Son was not "never leave Japan." It was that carrier wars in the United States punish optimism the way Vision Fund mark-to-market later punished unicorn math. SoftBank could still win pieces. It could not will an entire foreign telecom market into SoftBank Mobile's earlier Japanese playbook. That humility, uneven as it is, shows up later when Son talks about AI infrastructure needing power, chips, models, and robots together instead of one heroic acquisition.
Yahoo BB nights and the broadband grind
Before the Vision Fund made SoftBank look like a Silicon Valley weather system, Yahoo BB was the unglamorous survival engine. After the dot-com crash crushed SoftBank's equity story, Son leaned into pipes. SoftBank and Yahoo Japan built broadband offers that chased households with aggressive pricing and relentless marketing. Japan Telecom assets added residential and commercial subscribers. Debt piled up. Critics called SoftBank reckless. SoftBank called it necessary. The point of the broadband grind was not a pretty quarterly narrative. It was to keep SoftBank alive long enough for mobile internet and later for the investment holding company to matter.
Those years also trained Son's public stamina. He appeared in ads. He argued with regulators. He sold a future where always-on internet was normal. Japan's later smartphone boom did not start with SoftBank alone, but SoftBank's broadband and then iPhone exclusivity made the company feel culturally central in a way a pure software wholesaler never could. When modern SoftBank talks about happiness through the Information Revolution, the broadband decade is the uncredited middle chapter between warehouse SoftBank and Vision Fund SoftBank.
Portfolio weather: DoorDash gold, Didi frost, Oyo heat
Not every Vision Fund name was WeWork. DoorDash's public listing created enormous mark-ups that briefly made SoftBank look brilliant again. Coupang's U.S. listing similarly flashed value. Grab and other Southeast Asian bets fit Son's pattern of backing category consolidators. Fanatics sat in sports commerce. Uber remained a complicated public mark with soft and hard years. The portfolio was never only disasters. It was a barbell: some assets printed legendary returns on paper while others became case studies in governance failure and timing risk.
China was a special problem. SoftBank had ridden Alibaba to glory. Vision Fund exposure to Didi and other China tech names then met a regulatory crackdown that rewrote exit math. SoftBank cooled on China tech and sold Alibaba down. Son's long romance with Chinese entrepreneurship did not vanish overnight, but SoftBank's capital allocation after 2021 treated China risk as real, not theoretical. That shift matters for reading 2026 SoftBank: the emotional center moved toward OpenAI, Arm, U.S. and European data centers, and robotics, not another Hangzhou miracle.
Oyo and other SoftBank-linked consumer stories added a different kind of heat: aggressive expansion, founder drama, and valuation fights. Son's impatience, sometimes praised as decisiveness, could also force pace that local markets could not digest. Bloomberg and others chronicled moments when SoftBank's urgency looked expensive in hindsight. Son's own August 2022 shame comments covered that pattern without naming every scar.
The singularity slide deck as operating system
If you want to understand Son's recruiting pitch to princes, founders, and his own board, watch how he talks about singularity. It is not a side hobby. It is the operating system behind the Vision Fund, Arm, OpenAI, and Stargate. Computers already beat humans at chess, Go, and weather in narrow ways. Son's claim, repeated for years, is that within decades most domains of thought tip. SoftBank's job, in his telling, is to own the platforms under that tip: chips, models, power, and bodies for intelligence.
That is why the 2026 CEO letter spends so much time on Othello corners. Models without chips stall. Chips without power stay dark. Power without robots leaves intelligence trapped in chat windows. Robots without aligned intelligence scare the public. SoftBank's Cluster of No. 1 strategy is an attempt to hold enough corners that SoftBank becomes the default ASI platform company rather than a passenger. Skeptics hear empire cosplay. Believers hear a coherent industrial policy run through a public company. Both readings can be true at once depending on the quarter.
Family, identity, and the name he chose
Son's private life stays relatively guarded compared with American founder media cycles, but a few facts shape the public man. Marriage to Masami Ohno from Berkeley years. Two daughters. A younger brother, Taizo, who built his own entrepreneur-investor path through GungHo and Mistletoe. The SoftBank Hawks give Son a civic sports identity in Japan beyond balance sheets. The Tokyo and Woodside homes signal the wealth Alibaba and SoftBank equity created.
Identity remains the deepest early plot. Choosing Son over Yasumoto for professional life was not a branding exercise. It was a public alignment with Korean roots in a country where that choice still carried social risk for relatives. Nikkei and other outlets have described how SoftBank's CEO used his story to push back against anti-Korean bigotry. For a global magazine biography, the careful line is this: Son's minority childhood is documented by him and by major reporting; it helps explain drive without turning trauma into a motivational poster; and his later power did not erase the fact that he once needed a stranger at McDonald's Japan to tell him to leave.
Closing
Masayoshi Son's life keeps refusing a single moral. He is the bullied kid from Tosu who flew to McDonald's Japan for advice and then to Oakland with a suitcase full of urgency. He is the Berkeley student who sold a translator and arcade machines before SoftBank had a logo. He is the software wholesaler who named a company like a bank and meant it. He is the investor who saw Jack Ma's eyes and wrote twenty million dollars that helped seed a commerce empire. He is the carrier boss who brought the iPhone into SoftBank's Japan story. He is the man who lost tens of billions on paper in 2000 and lived. He is the man who raised a near-hundred-billion-dollar Vision Fund in the singularity's name and later said he was ashamed of how some of that capital performed. He is the chairman of Arm after Brexit, of Stargate after ChatGPT, of a SoftBank Group still stamped with his founding date from 1981.
In June 2026 he stood inside a rare week when SoftBank was Japan's most valuable company and his fortune printed near a round hundred billion, then watched the print fade within days. He answered with NAV charts and a rewritten life plan. The nineteen-year-old had scheduled a succession decade. The sixty-eight-year-old scheduled Artificial Superintelligence.
If you use a phone built on Arm ideas, ride a SoftBank-funded marketplace, ask ChatGPT a question partly underwritten by SoftBank capital, or walk past a Stargate construction fence in Texas, you are already inside his bet. Son did not invent every piece. He specialized in assembling pieces at a scale that frightens auditors and thrills pitch rooms. That is why his biography feels less like a product launch and more like a weather system: bright, sudden, expensive, and still moving.
Watch alongside this story
Short cuts from interviews, keynotes and launches. Each plays only the moment that matters.